Commercial property focus
Industrial, office, retail and other commercial property are valued on evidence relevant to their asset class.
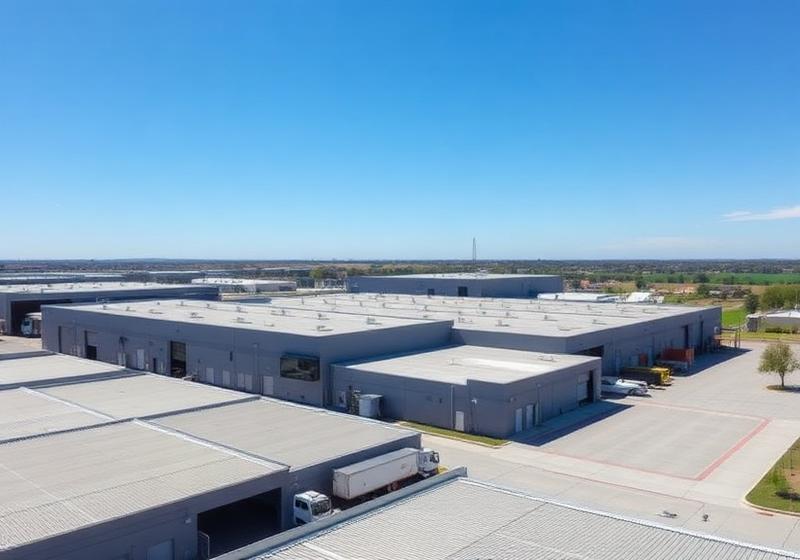
ElevateIQ valuers know industrial land has often grown faster than the building on it. We separate land rate, site coverage and surplus land, so your 30 June 2027 cost base reflects what a buyer would really pay. An AAPI Certified Practising Valuer signs every report, prepared on a desktop basis with an on-site condition record near the valuation date.
$500 + GST is applied in full against your valuation fee.
We confirm the scope, capture a condition record on site and analyse your local evidence. You receive one clear value, with every adjustment shown.
Land usually carries most of an industrial value. Our team analyses the land rate per square metre, site coverage, hardstand, clearance and truck access, then tests the result against leased and vacant sales in the same precinct. Surplus land is valued on its own line, so it adds its full weight to your cost base.
Our team records the land, improvements and tenancy, captures a condition record near the valuation date, then documents the approach behind the 30 June 2027 value.
Read the full CGT valuation guideProperty sales become public after settlement and registration. Many lease details do not. Rent-free periods, incentives, renewals and lease changes can stay inside agency files.
ElevateIQ analyses commercial sales and lease evidence from its agency network, then uses the most relevant transactions to support your valuation.
Dataset figures as at 31 August 2026.
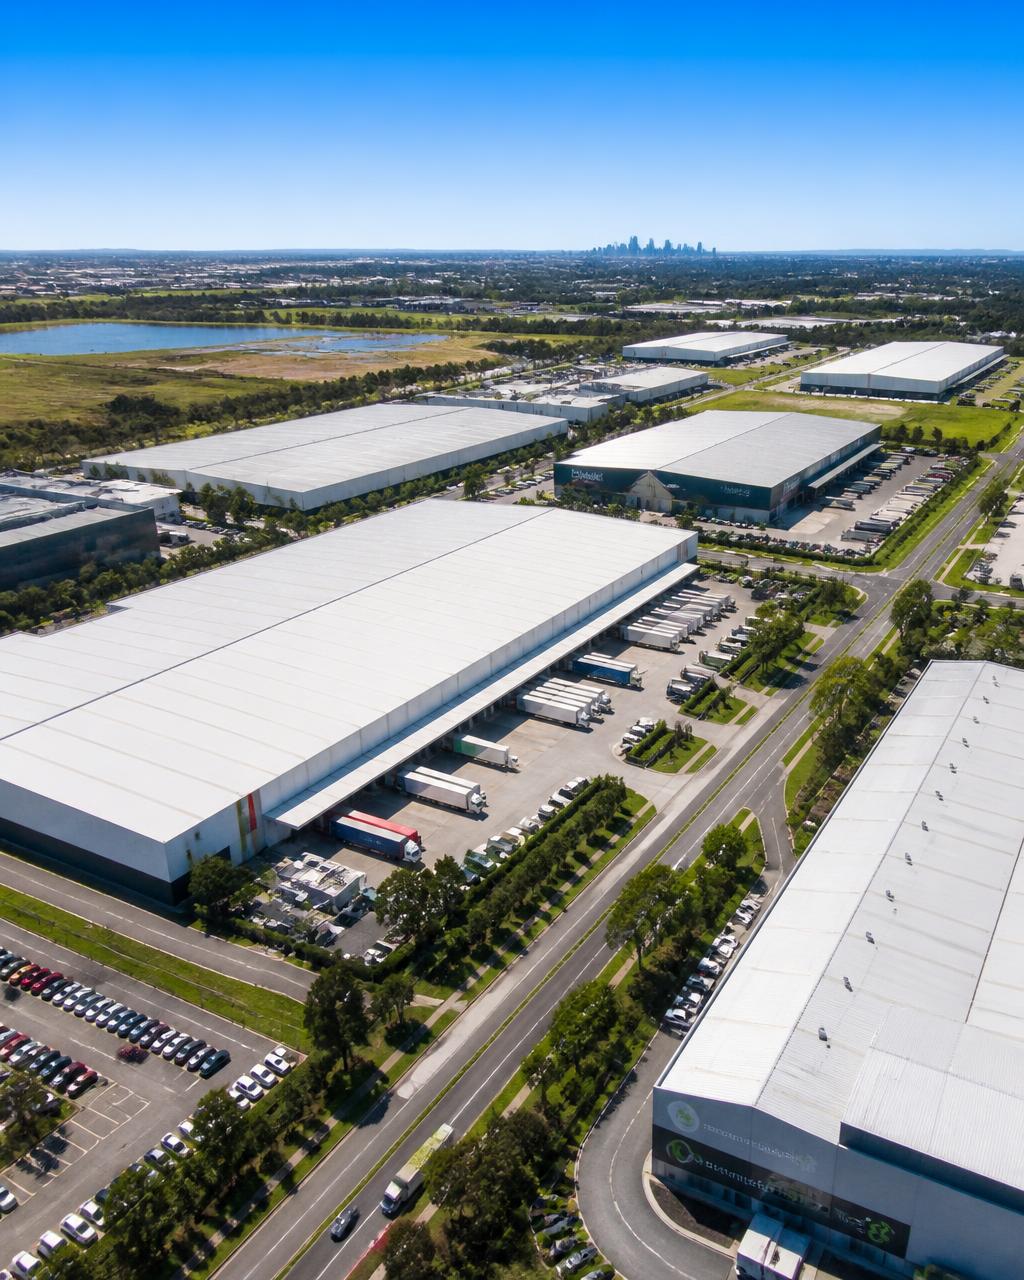
Commercial property valuation built around clearer evidence.
ElevateIQ values logistics facilities, manufacturing plant, multi-tenanted estates and industrial land across Australia. Every report is signed by an AAPI Certified Practising Valuer and tested against analysed transactions from our evidence network, around 19,000 sales and 25,671 lease transactions.
Industrial, office, retail and other commercial property are valued on evidence relevant to their asset class.
Relevant sales, market rents, lease terms and yields are reviewed before the final value is adopted.
The final report is reviewed and signed by an AAPI Certified Practising Valuer.
Local market evidence supports the 30 June 2027 value.
Each report records the site, improvements, title area and tenancy schedule before the market evidence is analysed.
Land rate, zoning, site shape and surplus land establish the base. Clearance, hardstand, truck access, power, floor loading and office fit-out show how useful the improvements are.
Lease term, options, reviews, tenant strength, outgoings and incentives affect income value. Vacant or partly leased assets place more weight on land and comparable sales.
The on-site condition record captures the site, improvements, title area and tenancy schedule. Direct comparison and capitalisation of market income are then reconciled to the 30 June 2027 market value.
You are named as a relying party. The non-editable PDF records the workings and is signed by a Certified Practising Valuer, giving your accountant and the ATO a clear basis for the adopted value and cost base evidence.
Fees are fixed and published on a two-axis schedule, the property's area band and its tenancy band, whichever produces the higher fee. Pricing starts at $1,500 + GST with your managing agent's details, or $2,000 + GST direct. The calculator returns your exact fee before you commit.
Published fees cover most properties. Larger or complex assets receive a written quote before work starts.
A useful valuation should show the evidence, the method and who signs the report.
Relevant industrial sales, market rent, lease terms and yields are reviewed for your property, not a generic rate per square metre.
A leased property may be valued on market income and yield. A vacant or owner-occupied property usually relies more on comparable sales.
The report states the market value at 30 June 2027, shows the evidence used and is signed by an AAPI Certified Practising Valuer.
The published fee, or an individual quote for a more complex property, is confirmed in writing before any work starts.
Start with the property address, owner details and basic property information.
We collect and verify title details, ownership records, lease information, plans and other property records.
The valuer reviews relevant industrial sales, market rent, lease terms and yields.
The final report states the market value at 30 June 2027 and is signed by a qualified valuer.
Your report records the 30 June 2027 market value from analysed property evidence, ready for your accountant.
For owners, trusts and advisers who need a supportable CGT cost base at the valuation date.
The signed report supports capital gains tax and ATO review. Accountants and registered tax advisers receive a documented market value.
Our team records title, ownership, land and improvements, including land area, zoning, warehouse utility, hardstand, access, improvements and tenancy.
Relevant industrial property sales, leases, market rent and yields are analysed and adjusted for material differences.
Direct comparison and income analysis are reconciled into a signed 30 June 2027 market value.
A signed valuation report that shows your property, the market evidence and how the final value was reached.
Fees are published, not quoted case by case. Enter the area and tenancy count and the exact fee, deposit and delivery month appear below.
Published fees cover most properties. Larger or complex assets receive a written quote before work starts.
Fill in the details to register your property
Your fee updates as you answer, and it stays on your screen until you choose to register.
Slot held from registration, no waiting for a quote.
One published fee per property, confirmed in writing.
Usually takes a few minutes. Fee confirmed in writing before you pay.
Add your managing agent's details in the form and the $500 reduction applies straight away.
Five clear answers before you register a property.
Many individual and trust owners choose to hold one, because the 30 June 2027 value applies whenever they sell. Your accountant confirms whether it suits your position.
The valuer measures the area a buyer could use or subdivide, applies a land rate from comparable site sales and lists it as a separate line, capturing its full contribution to your cost base.
Yes. The estate is valued as one asset with a full tenancy schedule. The tenancy band in the fee schedule reflects the additional lease analysis involved.
It is identified and valued separately within the report, because a buyer would pay for it separately. Ignoring it understates your cost base.
By a published two-axis schedule: your property's area band and its tenancy band, whichever produces the higher fee. Nothing is quoted case by case, so you can check the number yourself before registering.
Fixed fees from $1,500 + GST with your managing agent's details, or from $2,000 + GST direct. The $500 + GST deposit per property is applied in full against your fee.
Choose the report that matches the decision in front of you. Each one is signed and delivered with the evidence attached.
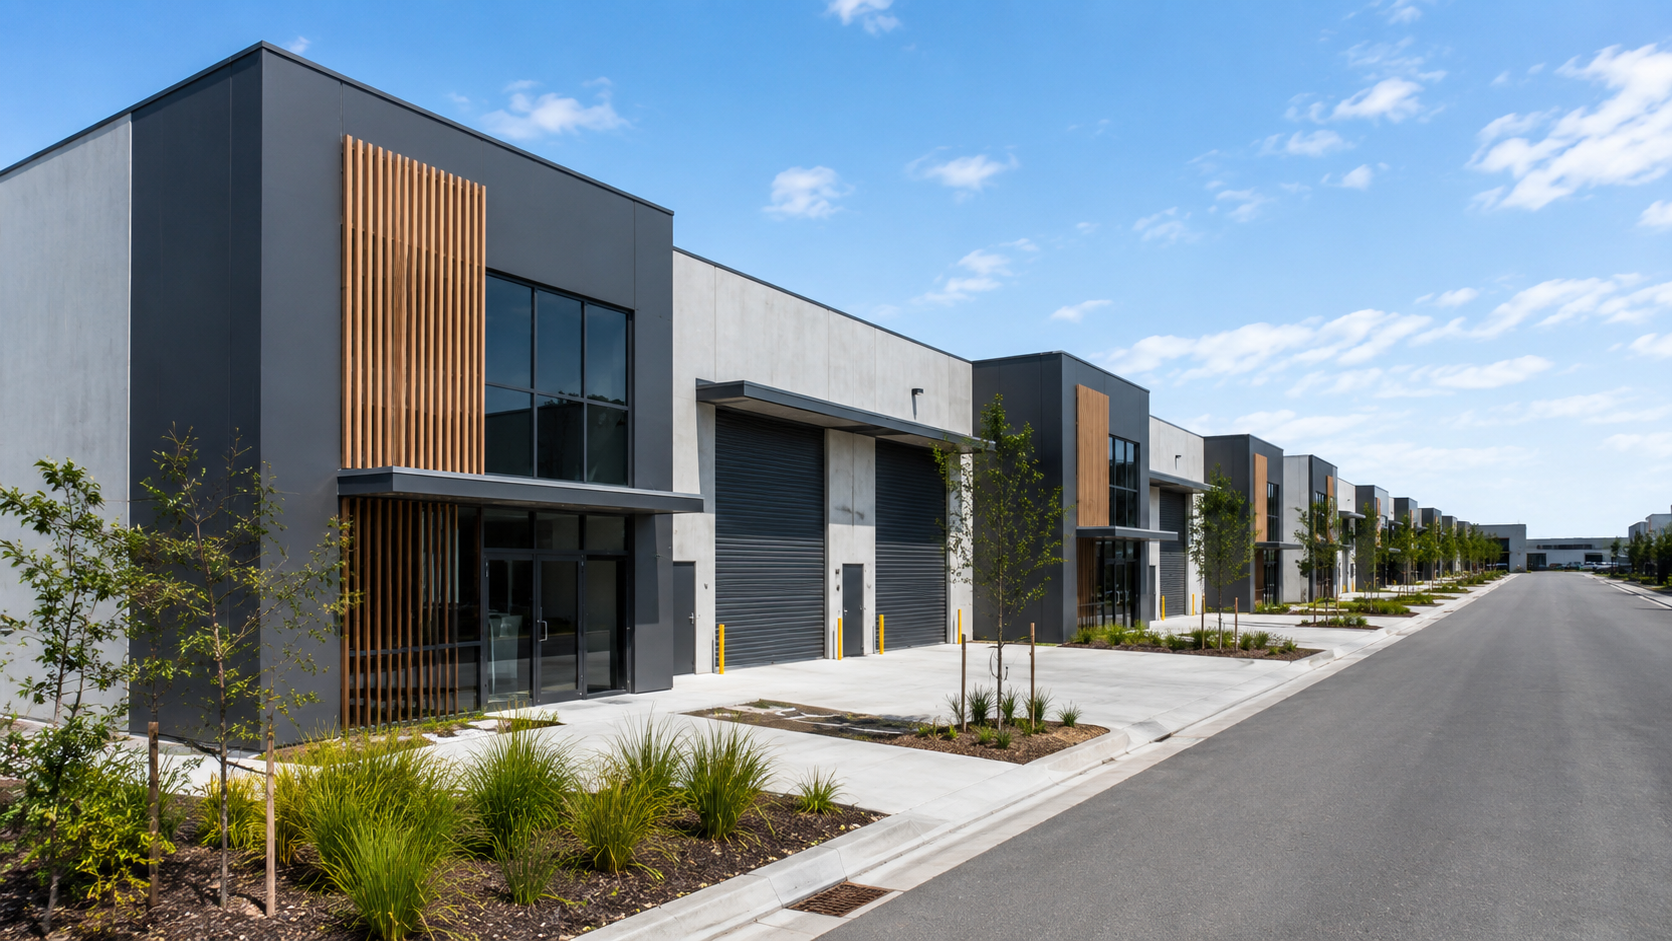
A current market value for a commercial property, delivered within 48 hours of acceptance.
Learn more
Market value evidence for your fund's annual audit or a member asset transfer.
Learn moreIndependent market rent evidence for lease renewals, rent reviews and negotiations.
Learn more