Property A
Industrial, Dandenong South
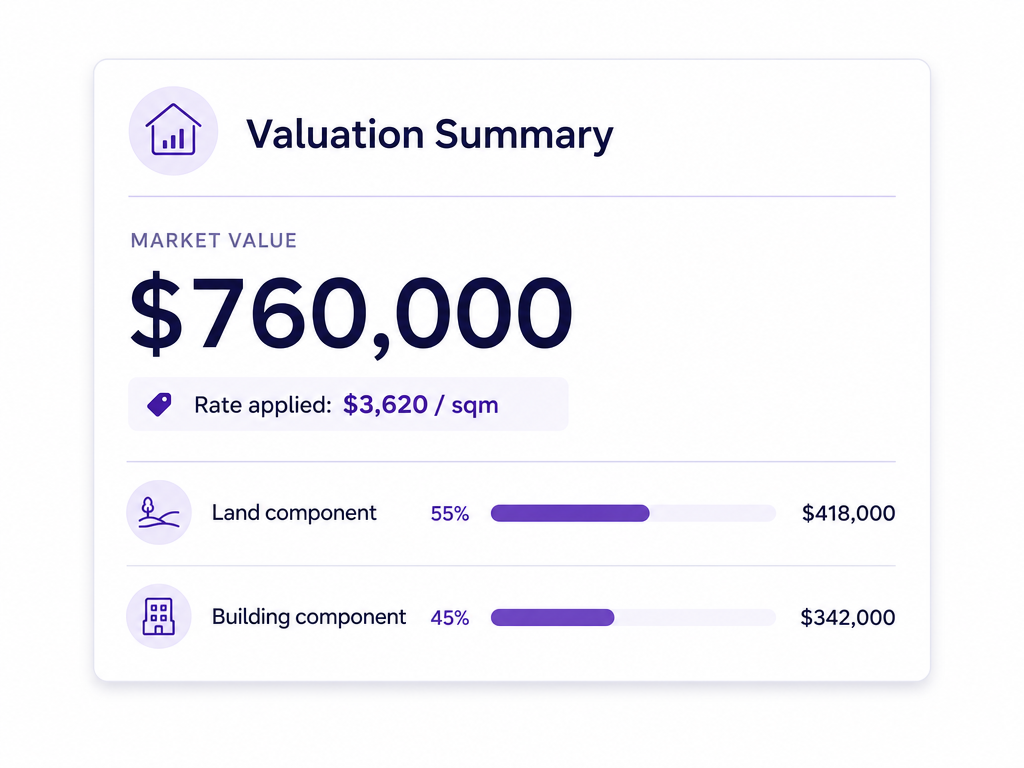
Value at 30 June 2027: $2,450,000
$1,250,000
$250,000
Pre-transition $1,250,000Post-transition $250,000
ElevateIQ values your commercial property for the 2027 capital gains tax transition, which splits your gain in two. A formula can set that split, or ElevateIQ’s signed valuation can set it using evidence specific to your property.
At the end of 30 June 2027, every capital gains tax (CGT) asset held by an individual or trust is deemed to be disposed of and immediately reacquired at market value. Nothing is sold, ownership does not change, and no tax falls due on the day. What changes is that the gain is split into a pre-transition and a post-transition component, and that split needs a number.
Without a valuation, a determined apportioning formula sets the split. It is a default, applied uniformly, and it takes no account of what actually moved the value of your building over your holding period, a lease signed at the right moment, a rezoning, a precinct that outran the metropolitan average.
A valuation replaces the default with evidence specific to the property. That is the whole of what it does.
An owner who holds a valuation and an owner who does not are not in the same position. One has two figures and can take advice on which applies. The other has one, and no way back to the date.
ElevateIQ prepares property valuations. We are not registered tax agents and do not provide tax, accounting or financial advice. Nothing on this page is advice about any person's circumstances.
Two commercial properties, both bought in July 2017 for $1.2 million and sold in July 2032 for $2.7 million. Both make a $1.5 million gain.
The formula splits that gain identically, because it reads dates and prices. One is a Dandenong South warehouse that ran hard to 2024 then flattened, the other a suburban office that recovered late. An accurate property valuation shows that difference clearly.
Property A
Industrial, Dandenong South
Value at 30 June 2027: $2,450,000
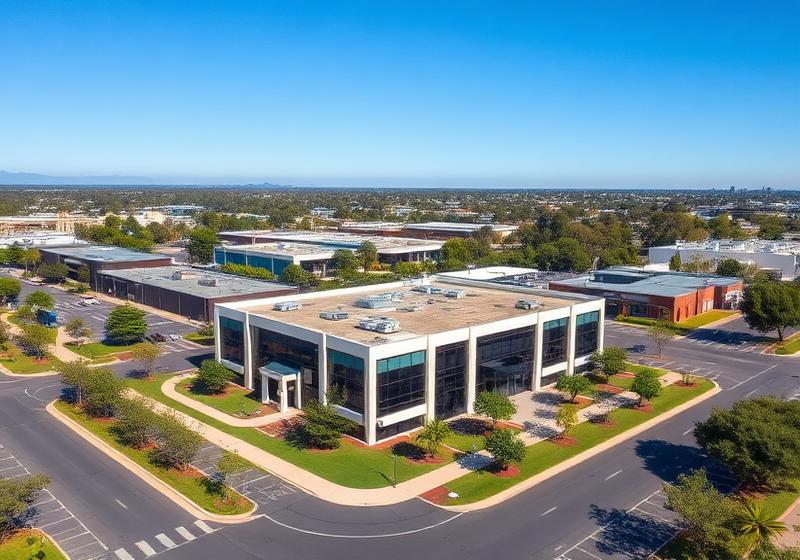
Property B
Suburban office, Box Hill
Value at 30 June 2027: $1,850,000
At 30 June 2027 they sat $600,000 apart. The formula returned the same number for both, because it reads dates and prices.
An accurate valuation shows exactly which property you own.
Your accountant decides which figure suits your position best. Property A holds more of the gain in the pre-transition component and Property B holds less, so having two figures to compare keeps the choice open to you.
Illustrative property imagery. Figures in this example are hypothetical and do not represent any actual property or transaction.
A legislative instrument sets the apportioning method, and it is not final yet. The formula figure shown is illustrative only.
ElevateIQ prepares property valuations. We are not registered tax agents and do not provide tax, accounting or financial advice.
Subdivision 112-E applies to capital gains tax (CGT) assets held by individuals and trusts. Companies sit outside it, with a limited exception for pre-CGT assets. An SMSF is a trust, but complying superannuation funds are dealt with under their own regime and are outside the transition, they carry a separate market value obligation every year.
| How the property is held | Position under Subdivision 112-E |
|---|---|
| Individual | Within scope, deemed disposal applies at market value |
| Family or unit trust (incl. corporate trustee) | Within scope, the trust is the relevant holder |
| Partnership | Within scope, the transitional rules reach partnerships |
| Company, asset bought after 20 September 1985 | Outside scope, companies keep their existing cost base |
| Company, asset bought before 20 September 1985 | Pre-CGT exception applies, confirm with your accountant |
| Self-managed super fund | Outside the transition, but an SMSF must hold market value evidence for its commercial property every year. SMSF appraisals from $650 + GST → |
Holding property in more than one structure? Common, and the two need different reports. A property in a family trust needs a valuation dated 30 June 2027; the same owner's SMSF property needs annual market value evidence instead. Register the first and we will scope the second at the same time.
ElevateIQ provides valuation services. Whether either suits your circumstances, and how your property is held, are questions for a registered tax agent.
Office, retail, industrial and showroom assets, where comparable evidence is harder to source informally than it is for a house.
Structures approaching succession, restructure or sale over the next few years.
Multiple assets, often held across different structures, each needing its own evidence at the same date.
Outside the transition, and an SMSF still reports market value every year.
Fill in the details to register your property
Your fee updates as you answer, and it stays on your screen until you choose to register.
Slot held from registration, no waiting for a quote.
One published fee per property, confirmed in writing.
Usually takes a few minutes. Fee confirmed in writing before you pay.
Add your managing agent's details in the form and the $500 reduction applies straight away.
Not before the date itself. A valuation states market value as at a date, so no report can state a 30 June 2027 value until 30 June 2027 has passed. A report signed in April 2027 states April value.
The ninety-day rule owners sometimes raise is a lender convention about how long a report stays current after signing. It runs backwards from the report date and does not allow a future date to be valued in advance.
So the work splits. Everything that does not depend on the date is assembled first; the figure comes last. Waiting also improves the report, sales settling near 30 June report late, and a file closed in October captures evidence a file closed in early July does not.
$500 + GST, applied in full against your fee. Written terms and a confirmed delivery month.
Title, tenancy schedule, condition record and comparable evidence. Where a partner agency manages the property, your property manager verifies the tenancy on site near 30 June.
Fixed by the Act. No report in this program can be signed before it.
Late-reporting June sales added, then an AAPI Certified Practising Valuer forms the opinion and signs. Delivered in your scheduled batch.
A Certified Practising Valuer, a member of the Australian Property Institute, bound by professional standards and carrying professional indemnity insurance behind the opinion. A real estate agent's appraisal is a different document and is not a valuation.
Where a market value position may later need to be substantiated, what is examined is whether the figure is supported by recent, relevant comparable evidence. That is why the comparable section is the longest part of every report we issue, and why the evidence base behind it matters more than anything else on this page.
Owners often already hold a number, an agent's appraisal from a sales pitch, a lender's figure from a refinance, or an automated estimate from a data platform. None of these state market value at a date in a form that can be relied on and tested.
An automated estimate is generated by a model and re-rates whenever that model updates, so the figure recorded today may read differently in six months with no record of why. An appraisal is an opinion given by a licensed agent, usually in a transactional context, and carries no professional indemnity behind the number. A valuation is dated, signed, built on identified comparable transactions analysed to a rate, and prepared by a valuer who has to stand behind it.
| Document | What it is |
|---|---|
| Automated estimate | Model output. Re-rates as the model updates. It reflects model inputs rather than a valuer's opinion dated to a point in time. |
| Agent appraisal | Opinion of a licensed agent, typically for a listing decision. Professional indemnity sits behind a signed valuation instead. |
| Valuation | Market value at a stated date, supported by analysed comparable evidence, signed by a Certified Practising Valuer, with the owner named as a relying party. |
ElevateIQ operates as an embedded valuation desk inside a network of leading commercial agencies across Australia, not as an external firm buying data in. Sales and leasing evidence flow from the network's own transactional activity and are analysed in-house as they occur. We receive about 1,600 new lease transactions per month across the network, have analysed 25,671 lease transactions all time and 18,671 commercial sales, a broader base of leasing evidence than the advertised market shows, and sales evidence months before it reaches the public record.
In partnership with
Sales are registered on title. The commercial terms of a lease live in the managing agent's file: the incentive, the rent-free period, the fitout contribution and the review mechanism.
Which means every leasing figure in every commercial valuation in Australia comes from relationships built deal by deal. The question is only whose relationships, and how many.
When a tenant renews, exercises an option or agrees a variation, no listing is created, no campaign is run, and nothing enters any public record. The negotiated terms exist in the managing agent's file and nowhere else.
In established commercial precincts, renewals and option exercises account for a substantial share of all leasing activity, and they price differently to a fresh letting on the open market, with different incentive structures and different effective rents.
Because capitalisation of market income is the primary approach, the assessment of market income is the most consequential input in the valuation. Evidence drawn only from new transactions is a shallow sample of the leasing market, and in some instances this can mean a market rent being adopted below current market levels, which can materially impact asset values.
That breadth of evidence is the structural difference between a valuation desk embedded in commercial agency practice and one working only from what is publicly visible, and it is what the market income assessment in the methodology rests on. Evidence is used only in aggregated, analysed form, individual leases and parties are never disclosed.
Evidence reaches most valuers by the public route: a deal is agreed, contracts exchange, settlement follows some weeks later, the transfer is registered, a data provider ingests it, and eventually it is published. By then the sale is commonly three to six months old.
Inside the network, the deal is known when it is done.
This matters most at the valuation date. Sales settling near 30 June 2027 will not appear in public records until late 2027 or beyond, which is precisely the evidence a 30 June 2027 valuation most needs, and precisely what a valuer working from published records will not have.
Dataset figures as at 31 August 2026, with ongoing transaction updates. Evidence is contributed under agreement with partner agencies and used in analysed form; individual transactions are not disclosed to third parties.
Industrial warehouses and factories, office buildings and strata suites, strip retail shops, and bulky goods or showroom premises, across every state and territory.
| Asset type | How the evidence is analysed |
|---|---|
| Industrial warehouse or factory | Building rate per square metre and underlying land rate, with yield where leased. Office component, clearance, access and site coverage recorded. |
| Office building or strata suite | Net lettable area rate and yield. For strata, the entitlement, owners corporation position and outgoings recovery are treated explicitly. |
| Strip retail shop | Depth-weighted rate reflecting frontage and Zone A, with yield and market rental evidence from comparable strip trading positions. |
| Bulky goods or showroom | Large-format rate and yield, with exposure, hardstand and main-road frontage carried through to the adopted rate. |
| Other commercial | Anything outside the published bands, including mixed use, medical, childcare and specialised premises. We quote these individually before any work starts. |
ElevateIQ values mixed-use assets on their dominant component and treats the balance separately.
Fixed-fee scopeSmall to middle markets commercial & industrial property
ElevateIQ designed the fixed-fee product for small to middle markets commercial and industrial property. We refer assets that need a different methodology or level of investigation for a scoped engagement.
Residential property
Houses, apartments and residential investment property sit outside this commercial valuation product.
Development sites and englobo land
Planning outcomes, feasibility and staging require a separately scoped valuation.
Specialised and going-concern assets
Hotels, service stations, childcare, healthcare and similar trading assets require specialist business and property analysis.
Rural and agricultural holdings
Water, soil, carrying capacity and agricultural infrastructure require a different evidence base.
Large or complex commercial assets
Properties above the published area and tenancy bands are reviewed and quoted separately.
Outside the fixed-fee scope does not automatically mean we cannot help.Send the property details and the valuation team will confirm the appropriate scope, fee and timing.
Every valuation report applies recognised property valuation methodology, so your accountant can show how the capital gains tax cost base was reached. Owner-occupier stock takes direct comparison as primary, with capitalisation as cross-check. Investment stock takes capitalisation as primary, with direct comparison as cross-check.
Primary approach for leased investment assets. Net market income capitalised in perpetuity at a rate derived from analysed sales, with the difference between passing and market income over the unexpired term adjusted separately rather than absorbed into the rate.
Applied to all assets, and the primary approach where the asset is vacant or owner-occupied. Analysed rate per square metre of lettable or building area, and per square metre of site area where the land component dominates, adjusted for location, size, configuration, condition, tenure and market movement to 30 June 2027.
Cross-check for multi-tenanted assets where lease events across the holding period materially affect the income profile.
Owner-occupied and specialised improvements. Land value on a comparable site rate, plus improvements on a depreciated replacement basis.
Areas follow the Property Council of Australia Method of Measurement. Net lettable area for office, gross lettable area retail for shops, gross lettable area for industrial.
Net market income assessed as gross market income less outgoings not recoverable from tenants, and stated separately from passing income. Face and effective rents distinguished, with incentives amortised over the lease term.
Yields reported on an initial, equivalent and reversionary basis where the passing income differs from market.
Weighted average lease expiry calculated by income, with the basis stated.
Capital adjustments itemised as explicit deductions after capitalisation, present value of under or over rent, letting-up allowance, incentive cost, outstanding capital expenditure and vacancy.
Highest and best use considered where the existing use is not the use a market participant would adopt.
Date of valuation
30 June 2027
The date the opinion speaks to.
Evidence reviewed
The records and market data
used to support the valuation opinion.
Date of report
When the valuer signed.
Required by API practice.
Every report states its scope, assumptions and limiting conditions, including the desktop basis of assessment and any information relied on without independent verification.
Read one before you pay for one. The specimen is a complete report on a synthetic property, same structure, same tables, same treatment of evidence as the report you would receive.
Site and lettable areas on a PCA measurement basis, planning zone, LGA and title particulars, with the source of each recorded.
Leases, terms, review mechanisms, expiries and WALE, with face and effective rents distinguished.
Each transaction analysed to a rate, attributes tabulated, comparability stated rather than implied.
Net market income and adopted rate derived from analysed sales, with under/over rent, letting-up, incentive and capital deductions itemised.
Capitalisation against direct comparison, with implied rate per square metre and implied initial yield tested against evidence.
Dates of valuation, inspection and report stated separately, assumptions and limiting conditions set out, relying parties named, CPV signature.
From $1,500 + GST per property with your managing agent's details, or from $2,000 + GST direct. A $500 + GST registration is applied in full against the fee. Answer four questions below and your fee, deposit and delivery month appear straight away.
Fill in the details to register your property
Your fee updates as you answer, and it stays on your screen until you choose to register.
Slot held from registration, no waiting for a quote.
One published fee per property, confirmed in writing.
Usually takes a few minutes. Fee confirmed in writing before you pay.
Add your managing agent's details in the form and the $500 reduction applies straight away.
Send the address first, then add the rest as your documents arrive. Your assessment starts the moment the property is registered.
Property address
Enough to open the file and hold your slot.
Ownership entity
The name the report is addressed to.
Lease details if tenanted
Current rent, term and outgoings treatment.
Recent property documents
Plans, schedules or a recent valuation if you have them.
Evidence is assembled by precinct and asset class, then analysed across the reports prepared in that batch. That reduces the marginal cost of each valuation without changing the valuation date, professional standard or signature.
We take on industrial, office, strip retail and showroom premises within a published schedule of area and tenancy bands. One published fee per property, with no scope creep at invoice.
| ElevateIQ | Traditional | |
|---|---|---|
| Signed by | AAPI Certified Practising Valuer | Certified Practising Valuer |
| Date of valuation | 30 June 2027 | 30 June 2027 |
| Evidence base | National network dataset, analysed in-house | Assembled per engagement |
| Property inspection | Desktop, with condition record and tenancy verification captured on site near the valuation date | Physical inspection by the valuer |
| Booking | Slot held from today | Subject to availability in the 2027 window |
| Example property | Market value | Traditional | ElevateIQ |
|---|---|---|---|
| Industrial warehouse2,500 sqm, 2 tenancies | $1,500,000 | $3,000 – $4,000 + GST | $1,500 + GST |
| Strip retail shop400 sqm, 1 tenancy | $800,000 | $2,000 – $3,500 + GST | $1,500 + GST |
Just note: Traditional valuation fees are indicative. Fees vary by provider, scope and location. ElevateIQ fees are per property.
If your managing agent is not already in the ElevateIQ network, add their details at registration and we reduce your fee by $500. Your fee drops to the partner rate straight away, there is no waiting and nothing to claim back.
We contact your managing agent as an introduction from you, and we say so.
If we are unable to confirm this agency manages your property, we will contact you and the direct rate will apply.
ElevateIQ produces reports in batches by precinct and asset class, and assembles the comparable evidence for each batch before production begins. We have to know which precincts we are covering before we can build the evidence for them, so the cohort closes at the end of February 2027, leaving March to build it.
ElevateIQ sets the cap against the number of reports our valuers can sign, not the number we could sell.
Registration takes about two minutes and $500 + GST secures the slot, applied in full against your fee. We confirm your delivery month by email the same day.
No subscription. One published fee, confirmed before you pay. Fee confirmed in writing before you pay.
Reviewed and signed by an AAPI Certified Practising Valuer
Every report is prepared under API professional standards and carries professional indemnity insurance, with you named as the relying party.
A property valuation determines market value at a point in time, so your report states the 30 June 2027 value set by tax law once that date has passed. A report signed in April 2027 states an April value.
We prepare your file from April to June 2027 and sign reports between July and December 2027, which keeps the evidence accurate and your timing comfortable.
The market value in your valuation report sets the cost base your accountant uses for the post-transition component of any later capital gain. Your registered tax agent applies that figure when the property is sold or another CGT event occurs, and includes the calculation in the relevant tax return.
Holding a signed valuation report means the cost base rests on analysed property evidence rather than a formula.
The valuation is prepared on a desktop basis, with a condition record near the valuation date capturing the building and site areas, condition, access, clearance and the tenancy position near the valuation date. Our valuers then analyse comparable sales and leasing evidence to a rate, apply capitalisation of market income and direct comparison, and reconcile the approaches.
The appraisal of the property is documented in the report so your accountant can see how the figure was reached.
Your accountant makes that call, and we help by showing the difference clearly. The formula applies a uniform method, while a property valuation applies market information and evidence specific to your asset at the date.
We prepare the valuation report so your registered tax agent has both figures to compare before lodging.
Then your accountant simply applies the formula, and you still gain from holding the valuation. It gives your registered tax agent two cost base figures to compare rather than one to accept.
Owners who hold a valuation keep that choice, since evidence for a past date is captured at the time.
Fixed fee from $1,500 + GST through a partner agency, or $2,000 + GST direct. Pay $500 + GST today, applied in full against your fee, and an AAPI Certified Practising Valuer signs the report.